


Note: This is an edited version of an article published earlier on our affiliates on 6 Nov 20.
Highlights
- LVGEM’s contracted sales in 1H20 plunged by 39.7% YoY to RMB 2.5 billion due to limited saleable projects over the period. However, the company plans to launch more property projects between 2H20 and 1H22. The aggregate saleable resources are expected to reach RMB 16 billion, while contracted sales are expected to rebound strongly.
- Cash and cash equivalents rose 28.0% YoY to RMB 10.7 billion, which were slightly less than the short-term debt, indicating some liquidity pressure. LVGEM is negotiating with investors to refinance a portion of its short-term debt. Specifically, USD 140 million of convertible bond and RMB 2.1 billion of onshore bond are expected to be replaced by longer tenure bonds, alleviating near-term debt repayment pressure.
- The LVGEM bond due 2023 is currently yielding 11.92%, above peers with similar credit profile. As the firm’s credit profile is overall decent and the outlook is promising, the bond seems to be a very attractive investment choice. The bond is available for transaction on Bond Express.
The USD 12% bond of LVGEM (China) Real Estate Investment Company Limited (“LVGEM”) was made available on Bond Express since August. In this article, we review the company’s 2020 interim results and analyze the bond’s investment value.
Operation highlights
Contracted sales plunged on limited saleable projects
In terms of contracted sales, LVGEM experienced a 39.7% decrease from RMB 4.1 billion in 1H19 to RMB 2.5 billion in 1H20. This was in line with our earlier forecast in April that contracted sales would drop in 1H20, as the company did not launch any new property projects during the period. In other words, all of the RMB 2.5 billion of contracted sales were from existing property projects, such as LVGEM Amazing Plaza in Shenzhen, LVGEM Joyful Town in Zhuhai, and LVGEM International Garden in Huazhou. Given the limited saleable resources, the plunge in 1H20 contracted sales was within our expectation.
With that said, LVGEM have released more saleable projects since June, including some premium projects like Zhuhai Dongqiao Urban Renewal Project. Aggregate saleable resources will reach RMB 16 billion for the 2H20-1H22 period, translating to an average annual saleable resources of RMB 8.0 billion in the next two years. Its contracted sales are expected to rebound strongly as a result.
The well-received Baishizhou Urban Renewal Project is proceeding as planned. LVGEM is working on the relocation contract agreement with households, and the process is expected to be completed by the end of this year. After the demolition of existing buildings, the group expects to commence phase one of the project in 2021, which should be launched for sale in 2023.
Commercial property business remained stable
Apart from the property development business, LVGEM also owns some commercial property projects, primarily comprising of office buildings and shopping malls in Shenzhen. The pandemic has caused a huge blow to the commercial property industry since 1H20 as vacancy rate for office buildings climbed 9 percentage points to 25.4% in Shenzhen, the highest among tier-one cities. Meanwhile, average rental rates also experienced a 13.6% decline, the largest decline for tier-one cities.
Surprisingly, LVGEM’s commercial property business remained stable as its occupancy rate was kept unchanged, and a few of its projects even performed better than expected. For instance, the NEO series of office buildings reported new lease signings for contracted area of 9,565 square meters, up 58% YoY. As a whole, the commercial property investment and operations segment delivered a rather decent result, with rental income rising 5.0% YoY to RMB 317 million for the first half of this year.
Credit profile
Cash balance grew with improved liquidity
As at 30 Jun 20, LVGEM had total interest-bearing debt of RMB 29.4 billion, out of which was short-term debt of RMB 10.9 billion, a 0.6% increase compared to the end of 2019. Long-term debt was close to RMB 18.5 billion, a 21.9% increase compared to the end of 2019. RMB 15.0 billion, or 51.1% of total borrowings, will mature within two to five years, which should allow the firm ample of time for fund raising and refinancing.
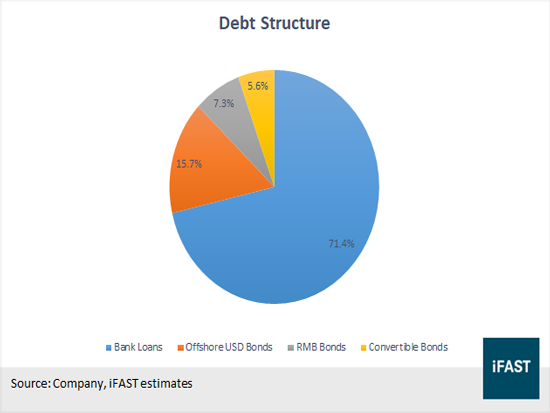
Looking at LVGEM’s debt structure (see Chart 1), bank loans, which were development loans for urban renewal projects, accounted for over 70% of debt. Due to the low interest of bank loans, LVGEM's weighted average borrowing cost stood at 6.9%, lower than the average of the real estate sector (7%), despite the 60 bps increase from the end of 2019. We believe LVGEM has a sound debt structure.
Chart 1: Debt structure (as at 30 Jun 20)
In terms of cash balance, LVGEM reported that the total cash balance was RMB 10.7 billion as at 30 June 2020, up by 28% YoY, translating to a cash-to-short-term debt ratio of approximately 1.0x. This was a slight improvement compared to 0.8x at end-2019. However, we think the cash position and overall liquidity are still tight.
On the other hand, as stated by the senior management, the company is negotiating with investors to refinance a portion of its short-term debt. Specifically, USD 140 million of convertible bond and RMB 2.1 billion of onshore RMB bond are expected to be replaced by longer tenure bonds. If LVGEM successfully carries out these transactions, the short-term debt amount would reduce by roughly RMB 3.0 billion, and the ratio of cash-to-short-term debt would increase to 1.4x, bringing a significant improvement to liquidity.
Based on LVGEM’s track record, we think the likelihood of the company being able to refinance its bonds is pretty high. LVGEM issued in March the USD 450 million of notes due 2023 to replace a USD 400 million bond that was due in August. The bond issuance was done concurrently with an exchange offer for the old bond, which had a satisfactory result with nearly 60% of bondholders accepting the exchange offer.
Rising leverage trend should reverse in the medium term
LVGEM’s leverage saw a significant rise as net gearing ratio stood at 147.7% as at 30 Jun 20, representing a 12.4-percentage point increase from 125.3% at the end of 2019. Only a handful of Chinese developers we track, such as Evergrande and Guangzhou R&F, had a higher net gearing ratio than LVGEM. Nevertheless, we do not think that LVGEM is close to insolvency, for the following reasons.
Firstly, compared to other high-turnover property developers, which regard cash collected from sold projects as their major fundraising source, LVGEM highly relies on bank loans as its urban renewal projects have a longer development cycle and it is the sole developer for most of these projects. As a result, the firm’s total debt would be relatively high versus peers. However, its reliance on bank loans is expected to decrease, along with leverage, after the Baishizhou project is launched for sale in 2023.
Secondly, as mentioned by management, LVGEM adopts the historical cost method to reflect the land value of its urban renewal projects. This approach disregards the potential value appreciation of these projects, thereby is likely to lead to an underestimation of the group’s total equity, which in turn skews the leverage ratio upward.
Table 1: Credit metrics
| RMB billion | 2019 | 1H20 | Change |
|---|---|---|---|
| Cash and cash equivalents | 8.4 | 10.7 | 28.0% |
| Short-term debt | 10.8 | 10.9 | 0.6% |
| Long-term debt | 15.2 | 18.5 | 21.9% |
| Ratio of cash to short-term debt | 0.8 | 1.0 | 25.0% |
| Net gearing ratio | 135.3% | 147.7% | +12.4 pp |
| Weighted average borrowing rate | 6.3% | 6.9% | +60 bps |
| Source: Company filings | |||
The LVGEM USD 2023 notes
As at 5 Nov 20, LVGEM's USD notes due 2023 are trading at a yield to maturity of 11.92% with 2.3 years to maturity. Considering that yields of B-rated Chinese property credits have generally reverted to the pre-pandemic level, and the fact that comparable bonds with similar credit profile and maturity are trading at 9-10%, we think LVGEM's USD notes due 2023 are reasonably priced. Also, as the firm’s credit profile is overall decent and the outlook is promising, we think this bond deserves to be highlighted for investors seeking high yields. It's worth mentioning that investors can transact in this bond through Bond Express.
Corporate risks
Investors should be aware of the following risks. Firstly, there are uncertainties about the Baishizhou project, which is currently at the stage of signing relocation contract agreement with households. The company might not be able to obtain the relevant permissions, such as "State-owned Land Use Permit", "Construction Land Planning Permit", "Construction Project Planning Permit", and "Construction Project Construction Permit" by its planned development schedule. In this case, there might be a delay for the project, and a postponed launch would adversely affect LVGEM’s sales performance, cash flows and debt repayment capability.
Besides, LVGEM failed to meet two out of three credit criteria in the recent "Three Red Lines" policy guideline. This would mean that its total debt can only grow at a maximum rate of 5% next year. Since LVGEM highly relies on external funding to meet the capital requirement for the Baishizhou urban renewal project, the company will probably face a wide funding gap if the government enforces the new policy strictly.
Conclusion
LVGEM’s contracted sales in 1H20 plunged by 39.7% YoY to RMB 2.5 billion due to limited saleable projects over the period. However, the company plans to release more property projects between 2H20 and 1H22. The aggregate saleable resources are expected to reach RMB 16 billion during this period, while contracted sales are expected to rebound strongly.
In terms of LVGEM’s credit profile, the cash-to-short-term debt ratio of just 1x implies a rather tight liquidity position, but the company is negotiating with investors to refinance a portion of its short-term debt. Specifically, USD 140 million of convertible bond and RMB 2.1 billion of onshore bond are expected to be replaced by bonds of longer tenure, alleviating near-term debt repayment pressure.
LVGEM’s USD notes due 2023 are currently yielding 11.92%, above peers with similar credit profile. As the firm’s credit profile is overall decent and the outlook is promising, the bond seems to be a very attractive investment choice. The bond is available for transaction on Bond Express.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in EVERRE 8.250% 23Mar2022 Corp (USD), EVERRE 7.500% 28Jun2023 Corp (USD), and LVGEM 12.000% 10Mar2023 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









